Blog
Plot Loan vs Composite Loan (Plot + Construction): Deadlines, Approvals and Planning Your Build in Coimbatore

Quick answer: A plot loan pays for the land. A composite loan (plot + construction) pays for the land and then for building the house, released in stages. Both are generally tied to an intention to build, often within a period the lender sets, so the land and the house should be planned together. In Coimbatore, check title and approvals before paying any advance, and confirm the loan’s deadlines and conditions with your lender.
“Can I get a loan for buying a plot?” and “what is a plot and construction loan?” are among the most common loan questions people search before building a house. A recurring worry in homeowner forums is what happens if construction does not start in time. This guide explains the difference between the two loan types, why the construction timeline matters, and how to plan the plot and the build as one project.
Infraura is a builder, not a lender, and does not arrange loans or handle loan paperwork. Loan terms differ between lenders and change over time, so confirm the details of your own loan with your lender before you plan around them.
Plot loan vs composite loan at a glance
| Question | Plot loan | Composite (plot + construction) loan |
|---|---|---|
| What it covers | Purchase of the plot | Purchase of the plot, then construction of the house |
| How it is released | At purchase | Plot part at purchase; construction part in stages as the house is built |
| Link to construction | Usually on the understanding you will build | Construction is part of the loan from the start |
| Key clause to read | Construction timeline and what happens if you do not build | Construction start and completion timeline, and stage conditions |
Why lenders link plots to construction
Housing finance is meant for homes, not land speculation. The Reserve Bank of India’s Master Circular on Housing Finance (2 April 2024, accessed 17 October 2026) says bank finance for buying a plot can be granted when the borrower declares an intention to construct a house on it, with bank finance or otherwise, within a period laid down by the bank. The period, and what happens if you miss it, is set in your loan terms. That is the clause to read twice.
Check the plot before you pay the advance
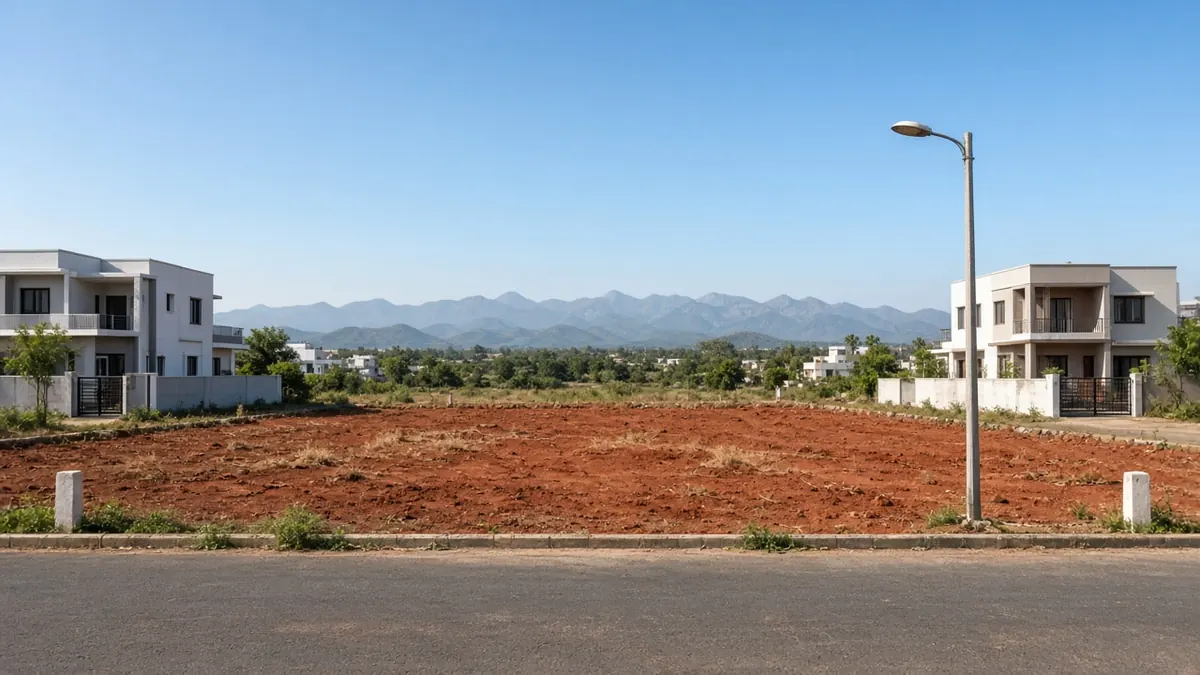
Homeowners in Coimbatore regularly ask about plots without layout approval, and about lenders turning them down. Before you commit:
- Title and land records: the sale deed chain, patta and encumbrance details should match each other.
- Layout approval: check that the layout is approved, or regularised for older plots. This also affects building plan approval later.
- Road access: width and legal status of the access road matter for approvals and for material lorries.
- What you can build: setbacks, floors and coverage allowed on the plot decide whether the house you want will fit.
- Soil and drainage: low-lying or filled land can mean a costlier foundation.
Our guide to building plan approval in Coimbatore explains what approval needs, and for compact plots our 30×40 plot construction guide shows how plot size shapes the house.
Plan the plot and the house as one project
If you are taking a composite loan, the build timeline is part of your loan. Treat it that way:
- Feasibility first. Before buying, check what can legally be built on the plot and roughly what it will cost. Ask an architect or builder to look at the plot and explain what it allows before you commit. Our construction services page covers house construction in Coimbatore.
- Design and approval next. Drawings and plan approval take time. Start them soon after registration so construction can begin within your loan’s window.
- A stage-wise schedule. Know when foundation, slabs and finishing are likely, so you can plan your own contribution and the stage releases.
- Services on the drawings. Electrical, data and CCTV points are best fixed at design stage. Get the wiring layout on the drawings before brickwork; see our smart home services.
- Supervision if needed. If you will appoint your own contractor or cannot visit often, a project management consultant can track quality and progress on your behalf.
Buying now, building later?
If you are buying a plot with no plan to build soon, read how your loan treats an empty plot over time. Homeowners report that some lenders change terms if construction does not happen within the agreed period. Ask the lender to explain, in writing, what happens at the deadline.
Questions to ask the lender
- Is this a plot loan or a composite loan, and what does each part cover?
- By when must construction start, and by when must it finish?
- What happens if the deadline is missed?
- What approvals do you need to see for the plot, and for the house?
- How will the construction part be released?
Frequently asked questions
What is a plot loan?
A plot loan funds the purchase of a residential plot. Lenders generally lend for a plot on the understanding that a house will be built on it. RBI's housing finance instructions say plot finance can be given when the borrower declares an intention to construct a house within a period set by the lender.
What is a composite or plot + construction loan?
It is a single loan that covers buying the plot and then building the house. The plot part is released at purchase and the construction part is released in stages as the house is built.
What happens if I don't start construction within the deadline?
That depends on your loan terms. Homeowners report that some lenders change the loan terms if construction does not start or finish within the agreed period. Read this clause carefully and ask the lender to explain it before signing.
Can I get a loan for a plot without layout approval?
Lenders generally look for clear title and proper approvals. An unapproved plot can also cause problems later with building plan approval. Check approvals before you pay any advance, and confirm with the lender.
Should I buy the plot and build later, or do both together?
If you plan to build soon, planning the plot and the house together lets you check that the plot suits the house you want and fits within the loan's timeline. If you are buying for the long term, check how the lender treats a plot that stays empty.
Can I start design before the plot is registered?
You can study feasibility, such as setbacks, orientation and floors allowed, but final drawings and approval should be based on the registered plot and its documents.
Talk to Infraura
Have a question about your project? Speak to our team in Coimbatore. We will explain the options plainly and give you a written scope.
- Call / WhatsApp: +91 96771 71707
- Email: support@infraura.com
- Visit: No:1499, Trichy Road, Coimbatore 641018
- Hours: Monday to Saturday, 10 AM to 7 PM